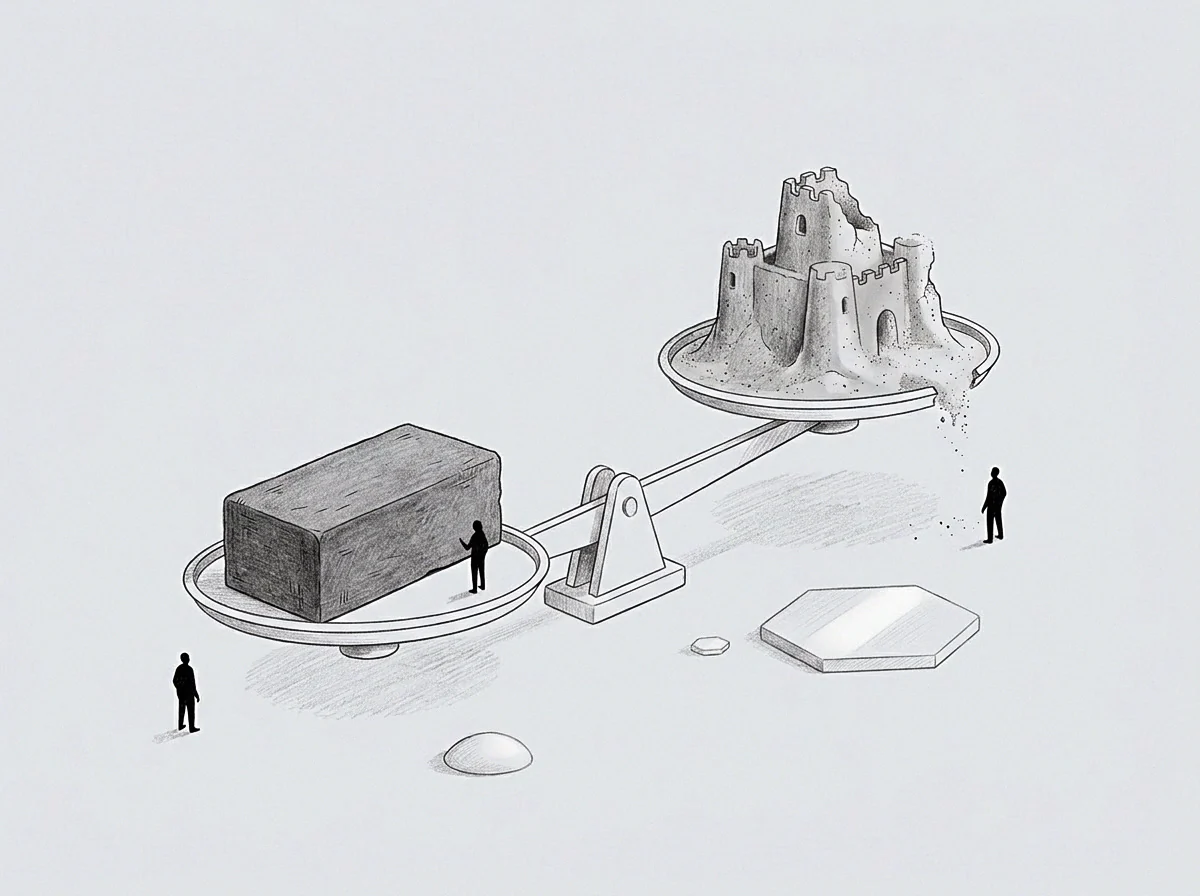
Meaning
Account revenue risk is the financial exposure carried within an enterprise client portfolio when customer billings contract, churn or fail to renew at expected intervals. Founders transitioning from product architecture to operational scale frequently underestimate this exposure because early growth hides individual contract decay behind aggregate top line expansion. Total financial vulnerability expands silently as the sales pipeline matures and customer acquisition costs mount without corresponding lifetime value retention.
Contract instability directly erodes enterprise valuation multiples by introducing unpredictable cash flow variance into statutory financial statements.
Revenue Exposure
Financial volatility manifests when customer agreements lack adequate minimum commitment clauses or carry penalty free cancellation options. Cash flow predictability degrades rapidly if a single enterprise client contributes more than a tenth of total monthly recurring receipts. Founders absorb this vulnerability as lost operating hours spent renegotiating terms or replacing defected clients under emergency conditions.
Concentration creates structural fragility that consumes available working capital before replacement streams can be secured.
Pipeline Decay
Early stage momentum often masks underlying customer dissatisfaction through rapid incoming volume that replaces silently departing accounts. Contract erosion accelerates when onboarding protocols lack dedicated accountability for post sale adoption metrics. Operational bandwidth drains away rapidly as technical teams divert focus from product roadmap execution toward defensive account retention efforts.
Customer churn signals deeper misalignment between contracted deliverables and actual operational utility within client environments.
Valuation Discount
Institutional investors apply severe valuation penalties to enterprises exhibiting high volatility in recurring revenue streams during funding rounds. Capital allocation committees discount future cash flow projections when historical customer retention rates display erratic cyclical patterns. Founders face depressed equity pricing and stringent liquidation preferences demanded by investors seeking protection against contractual instability.
Enterprise worth ultimately depends on contract durability rather than gross acquisition counts achieved during initial market entry.